Accelerated Compounding: Supercharging a Core SPY Portfolio with Tactical Debit Spreads
For long-term investors, the standard path to wealth creation is simple: buy and hold a broad market ETF like SPY and let market growth plus dividend reinvestment compound over time. While reliable, this “standard compounding” engine moves at the pace of the overall market.
By adding an asymmetric 30% Tactical Option Sleeve utilizing 60-to-90-day SPY Call Debit Spreads during confirmed uptrends, investors can transform standard growth into accelerated compounding without taking on unhedged leverage or naked option exposure.
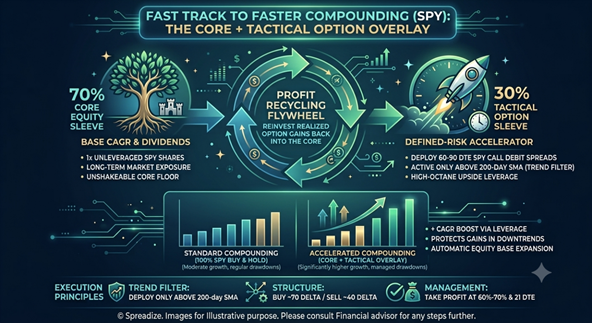
The Anatomy of the Strategy (70 / 30 Split)
Rather than risking 100% of your account in complex trades, the portfolio is divided into two distinct, synergistic sleeves:
- The 70% Core Floor: 70% of total capital remains locked in physical, unleveraged SPY shares. This core is held continuously to capture long-term market growth and dividend payouts while providing downside resilience during broad panics.
- The 30% Acceleration Overlay: The remaining 30% is deployed into 60-to-90 Day To Expiration (DTE) SPY Call Debit Spreads (e.g., buying a ~70 Delta ITM Call and selling a ~40 Delta OTM Call). This sleeve operates strictly when SPY is trading above its 200-day Simple Moving Average (SMA).
How Tactical Spreads Drive “Fast” Compounding
The overlay acts as a high-octane growth engine through three structural advantages:
- Defined-Risk Upside Leverage: A typical SPY debit spread costs around $8 to $8.50 for a $20-wide strike width. If SPY moves up moderately over 60 days, the spread yields a +130% to +150% return on the option debit. This allows a small fraction of capital to capture outsized upside gains.
- Controlled Volatility & Theta Decay: Selling the upper Out-of-The-Money (OTM) call offsets a significant portion of the time decay (theta) on the long call while capping downside risk strictly to the net debit paid.
- The Profit Recycling Flywheel: Realized option gains from the 30% sleeve are systematically swept back into buying more SPY shares in the 70% core sleeve. This permanently expands your underlying share base for the next market wave.
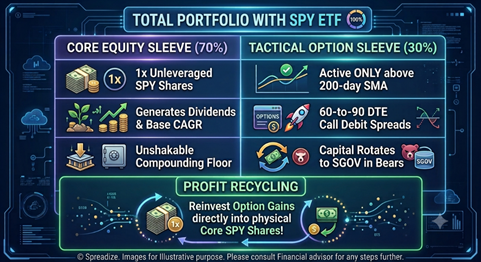
Protecting Capital in Bear Regimes Unhedged daily leveraged ETFs (like 2x or 3x funds) suffer severe volatility decay and catastrophic drawdowns during bear markets.
By tying the 30% tactical sleeve to a 200-day SMA trend filter, the strategy automatically moves the options sleeve into cash or short-term T-bills (such as SGOV) whenever the broad market enters a sustained downtrend. This preserves accumulated gains while the 70% core continues to collect dividends at the market bottom.
Option Structure & Strike Parameters
- Expiration / DTE: Target 90 Days to Expiration (90 DTE) to balance leverage against daily theta (time) decay.
- Strike Selection:
- Long Leg (Buy): ~70 Delta Call (In-The-Money / Near-The-Money).
- Short Leg (Sell): ~40 Delta Call (Out-Of-The-Money).
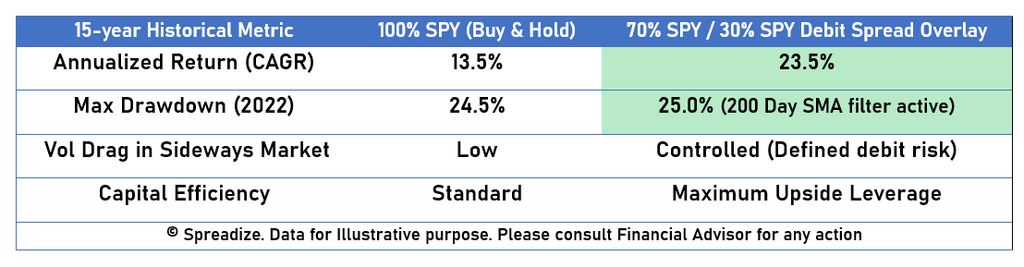
Net Cost & Payoff Example: On a $20-wide SPY spread, net debit is typically $8.50, offering a maximum potential payout of $20.00 (approximately +150% return on the 30% tactical sleeve if SPY rallies ~4–5% over 3 months).
Summary Checklist for Execution
- Trend Requirement: Deploy options only when SPY trades > 1.5% above its 200-day SMA.
- Structure: Buy ~70 Delta Call / Sell ~40 Delta Call with 60–90 DTE.
- Laddering: Split the 30% sleeve into monthly tranches to smooth out entry timing.
- Exit Rules: Take profit early at 60%–70% of max spread value or close at 21 DTE to avoid final-stage theta decay.
This may seem very complicated at start- but after careful observation – we are just using the bull-trend to boost our performance when market permits. This can be easily automated with today’s AI tools and can be tracked and controlled at precision. For more information contact Spreadize, where we can build similar custom portfolios to enhance gains